Quick answer: India VIX is a 30-day annualised implied volatility number, and on its own it tells a short strangle seller almost nothing. It becomes useful the moment you divide it. Divide India VIX by about 15.9 and you have the market's expected one-day move in the NIFTY, in percent. Multiply that by spot and you have it in points. Compare that number against the strike distance your strategy wants to sell, and you finally have a decision: sell as planned, widen and cut lots, switch to a defined-risk spread, or stay flat. Every step below is that one conversion, worked out in detail, with the band table our desk actually reads before the market opens.
This article is analytical research about a mechanical process. It is not investment advice, not a recommendation, and not a signal service. Read the disclaimer at the end before you act on any part of it.

What India VIX Is Actually Measuring
Full form and meaning. India VIX stands for India Volatility Index. It is the NSE's gauge of how big a move the market expects in the NIFTY 50 over the next 30 calendar days, worked out from live NIFTY option prices. The NSE brought it in during 2008 on the pattern of the CBOE's US VIX, which is why brokers call it the "fear gauge". A higher number means wider expected swings. A lower number means a calmer expected tape. It carries no view on direction.
India VIX is published by the NSE and is computed from the order book of near-month and next-month NIFTY 50 index options. It uses the variance-swap style methodology made popular by the CBOE and adapted for Indian markets: it reads the bid-ask quotes across the full strike chain, not just the at-the-money strike, and blends the two nearest expiries to produce a constant 30-day horizon. The output is expressed as an annualised percentage. The official methodology and the live index are on the NSE India VIX page, which is the one source to trust when the number matters.
Three things follow from the way it is built, and all three matter directly to a seller.
It is annualised. A reading of 14 does not mean the market expects a 14% move. It means the market is pricing 14% annualised standard deviation. That is the most common misreading, and it is also why most traders cannot connect a VIX print to a strike.
It is forward-looking and implied, not realised. It comes from what people pay for options right now, not from what the index has already done. So it carries a risk premium, and according to a long line of published studies on index options, implied vol sits above the vol that later shows up more often than not. That gap is the whole reason option selling has an edge.
It is 30 days. Always. Even on Tuesday afternoon with four hours to expiry, India VIX is still telling you about a 30-day window. That mismatch is not a rounding error, and one whole section below is devoted to it.
How the Number Is Built, Without the Maths
You do not need the formula to use India VIX, but a few inputs explain odd readings. The NSE takes the best bid and ask on out-of-the-money NIFTY calls and puts for the near-month and next-month expiries and uses the midpoint of each quote. The forward level of the index comes from the matching NIFTY futures price, and the strike just below that forward is treated as the at-the-money point. Calls above it and puts below it go into the sum. Time to expiry is counted in minutes, not days, and a risk-free rate for each expiry is part of the calculation. Where strikes are missing, a natural cubic spline fills the gap.
The output is the variance implied by those quotes, square-rooted and annualised, then blended across the two expiries into a constant 30-day figure. As the near contract runs out of time it is rolled out of the blend, so the number does not collapse into the final days (the NSE methodology paper on the page linked above has the exact rule).
One correction to a common broker explainer. Several describe India VIX as an average of Black-Scholes implied volatilities. It is not. The method is model-free in the CBOE style: it reads variance straight off the option quotes. A practical side effect is that the index is built from quotes, not trades, so a wide spread in a thin strike can feed into the number without anyone having changed their view of the market.
Most pages on this topic spend eight hundred words on the definition and then stop. The useful part starts now.
The Conversion Nobody Publishes: VIX to an Expected One-Day Move
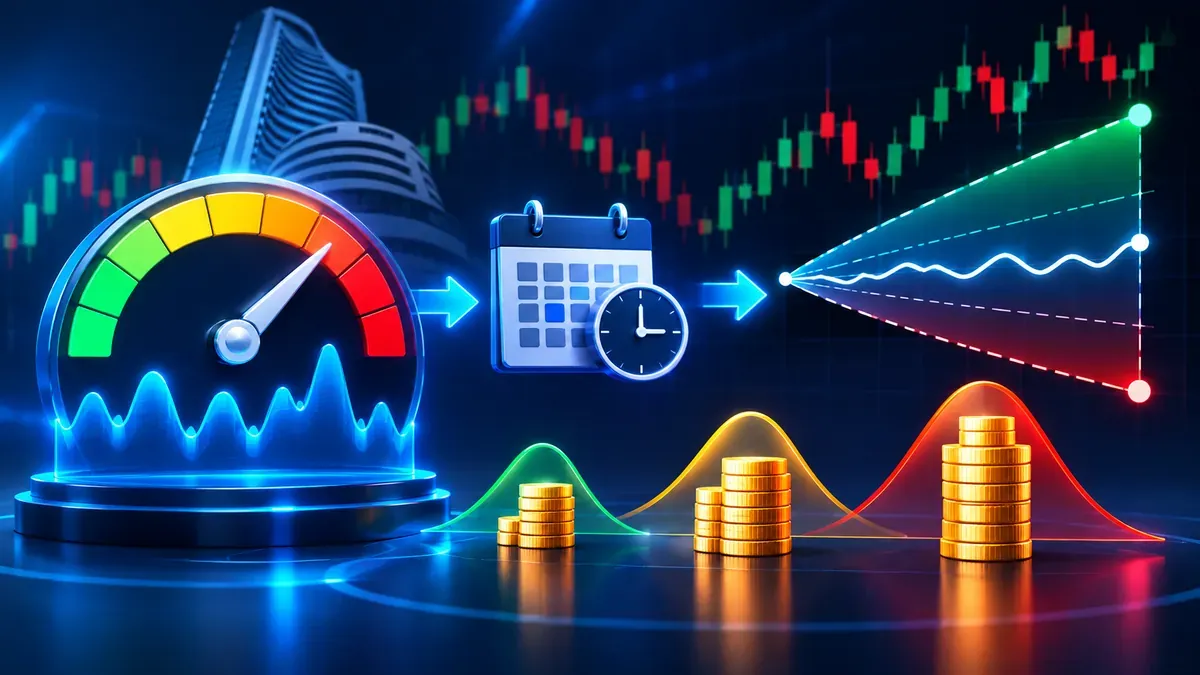
Volatility scales with the square root of time. To convert an annualised number into a one-day number, divide by the square root of the number of trading days in a year. Indian markets run roughly 250 sessions a year, and the square root of 252 is 15.87. Round it to 15.9 and the arithmetic becomes something you can do in your head at 9:05 in the morning.
Expected one-day move (%) = India VIX ÷ 15.9
Expected one-day move (points) = spot × India VIX ÷ 1590
That second form is the one to memorise. With the NIFTY around 25,000 (it closed at 25,030 on 6 November 2026), here is what three different volatility regimes look like in points.
VIX at 11. 11 ÷ 15.9 = 0.69%. On a 25,000 spot, that is 173 points. That is one standard deviation, which means roughly two sessions in three should land inside plus or minus 173 points and one in three should land outside it.
VIX at 14. 14 ÷ 15.9 = 0.88%. That is 220 points. A 250-point day, which feels ordinary, is now slightly more than a one-sigma event.
VIX at 20. 20 ÷ 15.9 = 1.26%. That is 314 points. The same 250-point day that was a one-sigma move at VIX 14 is now well inside normal, and the tail you need to survive has grown to roughly 630 points at two sigma.
Look at what happened across those three rows. VIX not quite doubled, from 11 to 20, and the expected move nearly doubled with it because the link is linear. Your premium roughly doubles as well. So far the trade scales cleanly. The problem, as we will see, is that not everything scales with it.
The Same Conversion, Out to Expiry
For a weekly strangle you rarely care about a single day. You care about the distance the index can cover between entry and expiry. Same square-root rule, different denominator: divide the annual figure by the square root of the number of periods.
For a full week, that is √52 = 7.21. For an arbitrary number of calendar days d to expiry, the general form is:
Expected move to expiry (%) = VIX × √(d ÷ 365)
At VIX 14 with seven calendar days left, that is 14 × √0.01918 = 14 × 0.1385 = 1.94%, or about 485 points on a 25,000 spot. At VIX 11 the same seven-day window prices 1.52%, about 381 points. At VIX 20 it prices 2.77%, about 692 points.
Those are the numbers your short strikes have to survive. Selling a strangle 400 points wide on each side at VIX 20 is selling inside a one-sigma move. Selling the same 400 points at VIX 11 is selling comfortably outside it. Same structure, same lot count, very different odds of being tested, and the only thing that changed was a two-digit number on the NSE site that most sellers glance at and ignore.
A Ready Reckoner, and the Rupee View
If you do not want to open a calculator at 9:05, keep this table. It is the same two formulas run for the VIX readings you are most likely to see, at a NIFTY spot of 25,000 and seven calendar days to expiry. The rupee column multiplies the one-day move by the NIFTY lot size of 65 (NSE cut it from 75 in the January 2026 revision; confirm the current figure on nseindia.com before you size anything).
| India VIX | 1-day move (1σ) | 1-day move per lot, index only | 7-day move (1σ) | ATM straddle, 7 days (approx) |
|---|---|---|---|---|
| 10 | 157 pts | ₹10,200 | 346 pts | ≈ 277 pts |
| 12 | 189 pts | ₹12,300 | 415 pts | ≈ 332 pts |
| 14 | 220 pts | ₹14,300 | 485 pts | ≈ 388 pts |
| 16 | 252 pts | ₹16,400 | 554 pts | ≈ 443 pts |
| 18 | 283 pts | ₹18,400 | 623 pts | ≈ 499 pts |
| 20 | 314 pts | ₹20,400 | 692 pts | ≈ 554 pts |
| 25 | 393 pts | ₹25,600 | 866 pts | ≈ 692 pts |
| 30 | 472 pts | ₹30,700 | 1039 pts | ≈ 831 pts |
Read the rupee column carefully. It is the index move times the lot size, which tells you how big the day is. It is not your strangle's loss. A short strangle leg that is 500 points out of the money moves by a fraction of an index point for each index point, so on an ordinary one-sigma day the position moves far less than this column suggests. The column matters on the bad days, when both the index and the premium on your short leg run against you together. Rescale for today's spot: the figures move one-for-one with spot, and with VIX.
From Expected Move to Premium: What Is Actually on the Table
The expected move tells you your risk. The next conversion tells you your reward. There is a clean approximation for the at-the-money straddle price that does not require running Black-Scholes (and if you want to see where the full model goes right and wrong on weekly NIFTY options, we have a Black-Scholes calculator note for that):
ATM straddle ≈ 0.8 × spot × σ × √(d ÷ 365)
The 0.8 is √(2/π), which falls out of the maths for an at-the-money option under a lognormal assumption. It is close enough for pre-market sizing, and it is wrong in the ways you would expect: it under-prices when the skew is steep and over-prices when the chain is thin.
Run it across the three regimes at seven days to expiry, spot 25,000:
| India VIX | 1-day expected move | 7-day expected move | ATM straddle (approx) | Straddle as % of spot |
|---|---|---|---|---|
| 11 | 173 pts | 381 pts | ≈ 305 pts | 1.22% |
| 14 | 220 pts | 485 pts | ≈ 388 pts | 1.55% |
| 20 | 314 pts | 692 pts | ≈ 554 pts | 2.21% |
This is the premium budget. Everything a short strangle can earn on that expiry is carved out of the straddle value, and a strangle by construction collects less than the straddle because both legs are out of the money. A strangle sold at roughly one standard deviation typically collects somewhere between 35% and 55% of the ATM straddle, depending on how steep the put skew is that week.
So at VIX 11, a one-sigma strangle is collecting on the order of 110 to 165 points. At VIX 20, the same structural trade is collecting 195 to 305. Against that you pay brokerage, exchange transaction charges, STT on the premium you sell, GST, stamp duty, and — much larger than all of those combined on a wide strangle — slippage on entry and, critically, on the stop-loss exit. Pull your last twenty contract notes and work out friction as a share of the premium you took in. Most retail sellers are surprised the first time they do it. At VIX 11 the same rupee cost is eating roughly twice the share of a thinner premium.
What Counts as High or Low? Brokers Disagree, So Count It Yourself
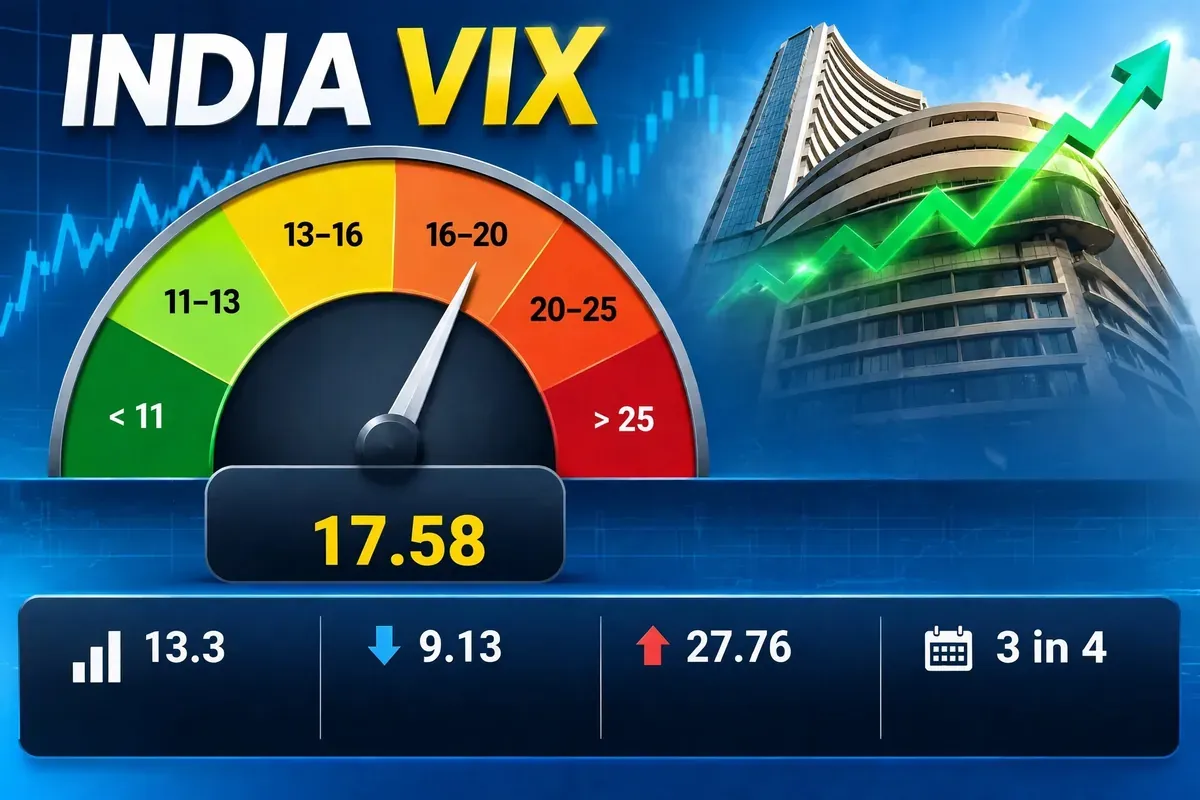
Search for the "normal" India VIX range and you get a different answer on every page. Zerodha's old Z-Connect explainer, written in 2014, calls above 25 high, below 15 low and 15 to 25 normal. Tradejini puts the normal band at roughly 11 to 17. Share India reads under 12 as complacent, 12 to 15 as normal and over 20 as high. Dhan's glossary calls 15 to 30 normal. They cannot all be right, and none of them tells you what the index has actually done lately. So here is the count.
This uses daily closing India VIX from our own data feed, 424 sessions from 2 January 2025 to 21 September 2026.
| India VIX close | Sessions | Share of sessions |
|---|---|---|
| Under 11 | 58 | 13.7% |
| 11 – 13 | 143 | 33.7% |
| 13 – 16 | 118 | 27.8% |
| 16 – 20 | 81 | 19.1% |
| 20 – 25 | 19 | 4.5% |
| Above 25 | 5 | 1.2% |
The median close was 13.3. The lowest close was 9.13 (26 December 2025) and the highest was 27.76 (30 March 2026). Three sessions in four closed below 16, and only 24 of 424, under 6%, closed above 20. A close above 16, which sounds middling in a textbook, sat in the top quarter of this sample. It is one 21-month window, not a law, but it is the reason the band table below uses cut-offs of 11, 13, 16, 20 and 25 instead of borrowing a textbook range.
Where it stands as of 9 November 2026. The NIFTY closed at 25,030 on Friday 6 November, up about 2%, and India VIX closed near 17.6, up about 13% on the day. Our feed shows 17.58 and press reports gave figures between 17.5 and 17.7, so check the NSE page for the official print. Two things stand out. A 17.6 reading sits in the 16 to 20 band, the "rich premium, market repricing something" row below. And VIX rose on an up day, the opposite of the usual rule of thumb, which is a fair reminder that the inverse link between the two is a tendency and not a law.
The VIX-Band Decision Table
Here is the table in the form we actually use. All point figures assume a NIFTY spot near 25,000 and roughly seven calendar days to expiry; rescale proportionally for a different spot, and by √(d/7) for a different number of days.
| VIX band | 1-day move | 7-day move | ATM straddle (% of spot) | Strangle strike distance (≈1.25σ) | Regime read |
|---|---|---|---|---|---|
| Under 11 | < 173 pts | < 381 pts | ≈ 1.2% | ≈ 475 pts | Premium is thin and friction is a large share of it. Defined-risk spreads or reduced size. Naked strangles are poorly paid here. |
| 11 – 13 | 173 – 204 | 381 – 450 | 1.2 – 1.45% | 475 – 565 pts | Selective. Workable for a disciplined seller with tight cost control, but there is no margin for a sloppy fill. |
| 13 – 16 | 204 – 252 | 450 – 554 | 1.45 – 1.8% | 565 – 690 pts | The core selling band. Premium adequately compensates a one-sigma strangle and the chain is usually liquid at the wings. |
| 16 – 20 | 252 – 314 | 554 – 692 | 1.8 – 2.2% | 690 – 865 pts | Rich premium, but the market is repricing something. Widen strikes, cut lots, keep total risk constant rather than scaling it up. |
| 20 – 25 | 314 – 393 | 692 – 866 | 2.2 – 2.8% | 865 – 1,080 pts | Defined-risk structures only. An unhedged strangle here is a bet that the repricing is wrong, which is a different trade from harvesting theta. |
| Above 25 | > 393 | > 866 | > 2.8% | > 1,080 pts | Event regime. Stand aside unless the position is fully hedged and the event date is explicitly in the plan. |
Paper trade this first. Every band, every strike distance and every threshold in this table should be run on your own data, with your own broker's costs and your own fill quality, for at least a full quarter of expiries before a single rupee of live capital is committed. The arithmetic is universal; the thresholds are ours, and ours were built against our own execution.
Two things about how to read the table. First, the strike distance column is a starting point, not a rule — 1.25 sigma is a reasonable default for a weekly strangle but the right multiple depends on your stop-loss policy far more than on the VIX band. A seller who exits at 1.5× premium can sit closer than a seller who holds to expiry. Second, the regime read column is about size and structure, not direction. Nothing here says the market will go up or down.
Why Low VIX Is the Dangerous Regime, Not the Safe One
The instinct is backwards. Low VIX feels calm, so selling feels safe. What actually happens is that your income shrinks faster than your risk does.
Work through it. Move from VIX 16 to VIX 11 and the premium on a comparably-positioned strangle falls by roughly a third. Now ask what happened to the things that can hurt you. A headline that gaps the index 1.5% overnight still gaps it 1.5%. That is 375 points at 25,000 whether VIX printed 11 or 16 the previous evening. Your margin requirement does not fall by a third. Slippage on a panicked stop-loss exit does not fall by a third either, and in a fast market it widens instead. Your brokerage and taxes are fixed in rupees per lot and unchanged.
So the ratio that matters — premium collected divided by the size of the adverse move you must survive — deteriorates in a low-VIX regime. You are being paid less to carry approximately the same tail.
And then there is the compounding problem: the temptation to fix it by selling more lots. A seller used to a set rupee figure per expiry sees premium fall by a third, and often sells 50% more lots to get back to the same income. That restores the income and raises the tail by 50%. It is the surest way we have seen accounts blown up, and it happens almost only in quiet markets.
India gave a textbook example of this run of events in 2024. India VIX spent April around 10 to 12, about as calm as the index gets, and then climbed into the counting of the Lok Sabha votes. On result day, 4 June 2024, it closed at 25.89, up 23.65%, which puts the previous close near 21. During the session it touched roughly 31.7. The NIFTY closed down 5.93% at 21,884.50, a loss of about 1,379 points, and traded as low as 21,281, roughly 8.5% below the previous close. A seller who had been comfortably harvesting 300-point straddles at VIX 11 in April, and had quietly increased lot count to compensate for thin premium, was carrying a position sized for a 170-point day into a session that closed at about eight times that and ran worse than that along the way. One market report had VIX back below 15 within about a week. The repricing came and went in days. The damage on a short book did not.
The lesson is not "avoid election weeks". Everyone knew that date was coming. The lesson is that the quiet stretch before the repricing is when the damage is set up, because that is when lot sizes quietly drift larger. By the time VIX is at 30 and screaming, the decision is easy. At VIX 10.8 in a sleepy April session, it is not.
India VIX Is a 30-Day Number. Your Expiry-Day Option Has Hours.
This gap matters most to anyone selling on expiry day, and it is why a trader can follow every rule above and still end up badly mispriced.
Apply the straddle approximation to an expiry-morning position. Say you are selling at 9:20 on expiry Tuesday with roughly six hours of trading left. Six hours is 0.25 of a day, or 0.25/365 = 0.000685 of a year; the square root is 0.0262. At VIX 14, the formula gives 0.8 × 25,000 × 0.14 × 0.0262 ≈ 73 points for the ATM straddle.
Anyone who has actually looked at the NIFTY chain on an expiry morning knows the ATM straddle does not trade at 73 points when VIX is 14. It trades meaningfully higher. The gap is not a flaw in the maths, it is the term structure. The implied volatility embedded in a contract with hours to live is a different number from the 30-day blend India VIX reports, and on expiry day it is routinely much higher, A fixed lump of intraday risk — the open, the first hour's direction, the 3 pm squaring — is being packed into a shrinking window.
Two practical consequences.
Use ATM IV, not VIX, for the trade you are actually placing. (If implied volatility itself is still fuzzy, start with our plain-English explainer on implied volatility.) Your broker's option chain publishes implied volatility per strike. On expiry day that is the number that prices your position. India VIX is the regime reading; ATM IV is the instrument reading. Mix the two up and an expiry-day straddle looks wildly overpriced, when in fact it is priced right for the hours it has left.
Watch the gap between them as information. When expiry-day ATM IV runs far above what the 30-day VIX implies, the market is pricing one near-term event, not general nerves. When the two are unusually close, the opposite. The spread between the two says more than either number alone, and it is free to work out from data already sitting on your screen.
The broader point: VIX sets the regime and the sizing envelope before the session. The instrument's own IV sets the strikes once the session is live. Use one where you should use the other and you get confident, well-documented, wrong decisions. Our own comparison of short straddles against short strangles for NIFTY weekly expiry goes into how the two structures respond differently to exactly this term-structure effect.
How Our Desk Uses the VIX Reading: A Gate, Not a Signal
The distinction is everything, so it is worth stating plainly. A signal tells you to enter or exit. A gate tells you whether the strategy you already selected is allowed to run today, and at what size.
We have been building and backtesting systematic index-option selling since 2006, and the rule that has survived every revision of the system is this: the regime picks the configuration, and it picks it before the session opens, not during it.
In practice that means the pre-market read on India VIX determines which configuration from the tested set is eligible, what the lot count is, and what the strike distance will be. Once the session starts, that decision is frozen. We do not widen strikes at 11 am because the market moved. We do not add lots at 1 pm because premium looks attractive. Changing the setup mid-session is a discretionary override in a systematic costume, and every case of it in our own logs turned out worse than the decision it replaced.
The reason is straightforward. A setup only means something if it was backtested as one unit over a large sample of similar sessions, and a setup pieced together live at 11 am has never been tested at all. Whatever edge you thought you had is gone, because you are no longer running the thing you measured. This is the discipline that separates an engineered strategy set from a set of habits.
For a different example of a clean-looking threshold rule that stops working on expiry day, see why the PCR rulebook breaks on expiry day.
The second-order benefit of a gate is that it makes "no trade" a legitimate output. Discretionary sellers almost never choose to sit out, because sitting out feels like failure. A gate that says "VIX is 9.8, this configuration is not eligible" removes the emotion from the decision entirely. Over a year, the expiries you skip contribute as much to the result as the ones you take.

What India VIX Does Not Tell You
A short list, because the omissions are as important as the conversions.
Direction. India VIX is a magnitude, not a vector. It tends to rise when the market falls, because falling markets make people buy puts, and people mistake that link for forecasting power. It also reacts harder to falls than it relaxes on rallies. But a high reading does not call a decline, and the link breaks often enough to matter. On 6 November 2026 the NIFTY gained about 2% and India VIX gained about 13% in the same session. Tradejini makes the same point about Budget and RBI policy days, when the index can sit still while VIX stays high. A high reading forecasts a wider range in either direction.
Gap risk. The whole method above assumes prices move in small steps, and overnight gaps break that assumption outright. India VIX prices what is expected over a 30-day window on average; it does not price the odds that a global session, an overnight policy move or an offshore shock puts the index 2% past your short strike before the market even opens. A strangle seller's worst days are almost always gap days, and the expected-move maths will not warn you.
Event risk on named dates. Union Budget day, monetary policy announcements, election counting days, major global central bank decisions. These are known well in advance and they belong on a calendar, not in a volatility index. VIX does pick them up as they draw near, but by then the premium has already repriced. The calendar has to be checked independently. The usual pattern is that VIX holds up into a known event and deflates right after it, even if the index goes nowhere. A seller who sells the day before and watches premium shrink after the event is collecting that deflation. Do not mistake it for a read on where the market is going.
Liquidity at your strike. A calm VIX reading says nothing about whether there is a two-way market 700 points out of the money on an expiry-day afternoon. Check the bid-ask spread and the open interest at the exact strikes you intend to sell, which is the argument of our liquidity-before-IV note on strike selection. Wide wings in a thin chain are where paper edge dies on the exit.
Your own risk capacity. Obvious, and always forgotten: the band table above assumes a size you can carry through a two-sigma move against you with no forced exit. If your margin utilisation is already at 90%, no VIX reading makes the trade appropriate.
A Plain Pre-Market Checklist
Five steps, executable in under three minutes before the open.
1. Read the India VIX close from the previous session and the pre-open print. Note both the level and the direction of change over the last three sessions. A VIX of 14 that has fallen from 19 is a different environment from a VIX of 14 that has climbed from 11.
2. Convert to the expected move. Spot × VIX ÷ 1590 for the one-day figure. For the expiry window, spot × VIX × √(days ÷ 365). Write both numbers down.
3. Compare against the strike distance the strategy wants. If your configuration wants to sell 500 points out and the expiry-window expected move is 690 points, you are selling inside one standard deviation. That is a legitimate choice, but it must be a choice, not an accident.
4. Check the named-event calendar. Policy dates, result dates, expiry-day quirks, and any scheduled global event that lands inside your holding window.
5. Size down or stand aside if steps 3 and 4 disagree with the configuration. The default action when the gate fails is no trade. Not a smaller version of the same trade improvised on the spot — either the tested reduced-size configuration, or nothing.
That is the whole process. It is meant to be boring, and it is meant to be finished before the first tick prints, because the whole value of a gate is that it gets decided when nothing is at stake.
VIX is a month-ahead number. For the intraday view of the premium itself, the straddle chart shows what the market is charging minute by minute on expiry day.
Frequently Asked Questions
Is high India VIX good for option sellers?
High VIX means more premium, which is attractive, but it also means the market is pricing a wider range and usually repricing a specific risk. The premium is higher because the risk is higher, not instead of it. A high VIX works for sellers who widen strikes and cut lots so total risk stays flat, and it is dangerous for sellers who keep the same strikes and simply enjoy the fatter credit. Above roughly 20, defined-risk structures make more sense than naked strangles.
What India VIX level is too low to sell options?
There is no universal number, because it depends entirely on your cost structure. The right test is a sum, not a threshold: work out the premium your setup would collect at today's VIX, subtract full round-trip friction with slippage included, then ask whether what is left still pays you for the tail you carry. For most retail cost structures that calculation starts looking poor somewhere in the 10 to 11 region, which is why our band table treats sub-11 as spreads-or-smaller-size territory, not a normal selling market.
What is the difference between India VIX and ATM IV?
India VIX is a constant 30-day annualised volatility figure computed across the whole NIFTY option chain from the two nearest expiries. ATM IV is the implied volatility of one specific at-the-money contract with its own specific time to expiry. The two split apart whenever the term structure is not flat. On expiry day they split sharply, because the contract you sell has hours of life while VIX still describes a month. Use VIX to set the regime and your sizing envelope; use ATM IV to price the actual trade.
Does India VIX predict market direction?
No. It measures the expected size of a move, not its direction, and while India VIX and the NIFTY do move opposite each other because fear bids up options when markets fall, that is not the same thing. That is a description of what tends to happen at the same time, not a forecast. A rising VIX tells you to expect a wider range and to size accordingly. It does not tell you which way.
How do I convert India VIX into an expected NIFTY move in points?
For one day, divide VIX by 15.87, the square root of 252 trading days, to get the expected percentage move, then multiply by spot. The shortcut is spot × VIX ÷ 1590. For a longer window, multiply VIX by the square root of (calendar days ÷ 365) and then by spot. At VIX 14 with the NIFTY at 25,000, that is roughly 220 points for one day and roughly 485 points over a seven-day expiry window. Both figures are one standard deviation, so expect the index to finish outside them about a third of the time.
Where can I read India VIX live?
The source to trust is the NSE's own India VIX page, which carries the live index next to the method used to build it. Most broker terminals and finance portals show the same value with a short delay. For a pre-market gate, the previous close plus the pre-open print is sufficient; you do not need a tick-by-tick feed to make a sizing decision.
Should I change my strangle mid-session if India VIX spikes?
Changing the setup mid-session means running an untested structure. Our rule is that the regime picks the setup before the open, and the choice is then frozen. A VIX spike during the session is handled by the stop-loss and exit rules you already set, not by making up new strikes. If vol spikes keep hurting a setup, the fix belongs in the backtest and the pre-market gate, not in the live session.
What is the full form of India VIX?
India VIX stands for India Volatility Index. It is published by the NSE and measures the volatility the market expects in the NIFTY 50 over the next 30 calendar days, as an annualised percentage. The VIX label comes from the CBOE Volatility Index in the US, which the Indian version is modelled on.
What does an India VIX of 20 mean?
It means NIFTY option prices imply an annualised volatility of 20%. That is not a forecast of a 20% move. Divide by about 15.9 and you get roughly 1.26% for one day, which is about 314 points with the NIFTY at 25,000. Over seven calendar days the same reading implies about 2.8%, or roughly 690 points. Both are one standard deviation, so the index should finish outside them about one time in three. A VIX of 20 says to expect a wider range, not which way it will break.
Why does India VIX fall after an event?
VIX carries a premium for uncertainty that the market is waiting to see resolved, such as an election result, a Budget or a policy decision. Once the event passes the uncertainty is gone and option prices come down, even if the index barely moves. After the June 2024 counting day, one market report had VIX back below 15 within about a week of an intraday high near 31.7. A falling VIX does not say the market will rise. It says the expected range has narrowed.
Can I trade India VIX directly?
Not the index itself. The NSE has listed India VIX futures, and some broker explainers point to them, but trading in them has been very thin, and Zerodha's own replies to readers over the years say they were barely traded. Check with your broker whether any contract is actually available before you plan around one. We do not trade them. We use VIX as a gate on the size and shape of an option-selling setup.
The Bottom Line
India VIX is not a number to watch. It is the input to a fifteen-second sum that turns a market-wide vol reading into the two figures a short strangle seller actually needs: the expected move over the holding window, and the premium that move justifies. Every ranking page for this keyword will show you the live quote. Almost none of them will show you the division.
Do the division. Compare the result to the strike distance your strategy wants. If the two disagree, the strategy loses — reduce size, widen, switch to defined risk, or skip the expiry. That is the entire discipline, and it is worth more than any indicator overlay.
To see how this gate is wired into a tested, rule-based system rather than a manual habit, our NIFTY and Sensex algo trading framework sets out how regime detection, setup choice and position sizing fit together before the session opens. For the income side of the same question, the write-up on option selling for monthly income on NIFTY works through what these premium figures add up to over a year, and what they do not.
Important Disclaimer
EliteAlgo provides analytical software, backtesting infrastructure, and educational research on systematic trading strategies. EliteAlgo is not a SEBI-registered investment adviser, and nothing in this article constitutes investment advice, a trading recommendation, or a solicitation to buy or sell any security or derivative contract. Options trading, and index option selling in particular, involves substantial risk of loss, including losses that can exceed the premium collected on undefined-risk (naked) structures, and is not suitable for every investor. All volatility bands, strike distances, conversion factors and thresholds in this article are illustrative of a method, not recommendations, and are stated against an assumed NIFTY spot level that will not match today's. Lot sizes, margin requirements, transaction charges, expiry conventions and contract specifications are revised periodically by the exchanges and must be verified independently on nseindia.com and sebi.gov.in before any trading decision. Past performance of any strategy, backtest or historical volatility regime is not indicative of future results. Consult a SEBI-registered investment adviser regarding your specific financial situation before trading in derivatives.
Author: Rajeev Gupta, Founder of EliteAlgo. EliteAlgo has built and refined systematic algo trading and backtesting infrastructure for Indian index derivatives since 2006, across multiple market cycles and volatility regimes.