Open the straddle chart on any broker terminal during NIFTY expiry and you will see one line. It mostly slopes down. Now and then it jumps. Sometimes it sits flat for twenty minutes. Most people stare at the level and ask whether 140 is high or low. The better question is whether the line is doing what a line normally does at that time of day.
To answer that, you need two things: a clear idea of what the line actually measures, and a baseline for how it usually behaves. This page gives you both. The baseline comes from our own work: we rebuilt the straddle line minute by minute for 62 NIFTY and 62 SENSEX expiry sessions and measured it. Where a number below is ours, it comes from that run. Where we do not have a number, we say so.
Short version: a straddle chart adds the call and put premium at one strike. A rolling ATM chart tells you what the market is charging for movement and time right now. A fixed-strike chart tells you what a position you already hold is worth. On expiry day the rolling line falls along a fairly predictable curve, and the afternoon is where it stops being predictable.

What a Straddle Chart Plots
A straddle is a call and a put at the same strike and the same expiry. The chart plots their combined premium over time, usually one point per minute. On Tuesday 2 September 2025 at 9:20 the index was at 24,654, so the ATM strike was 24,650. The call traded at 46.9 and the put at 37.15, so the straddle read about 84.
Units matter, because people mix them up. The line is in index points. One point is worth Rs 65 on a NIFTY lot (lot size 65) and Rs 20 on a SENSEX lot (lot size 20). As of November 2026, NIFTY weekly options expire on Tuesday and SENSEX weekly options on Thursday, shifted a day earlier when the exchange is shut. NIFTY strikes are 50 points apart. SENSEX strikes are 100 apart, which is a finer grid relative to the index level, and that matters later.
Because the premium is the sum of two legs, the line carries three things at once: where the index is relative to the strike, what implied volatility is doing, and how much time is left. Everything below is about telling those three apart.
Rolling ATM vs Fixed Strike: Pick the Right Line
This is the part most explainers skip, and it is the biggest source of confusion. There are two different charts that both get called a straddle chart.
- Rolling ATM straddle. Every minute, the tool finds the strike nearest the index and adds that strike's call and put. The strike changes during the day, so the line is not one position. It is a gauge: roughly, implied volatility multiplied by the square root of the time left. This is what most live straddle tools draw by default.
- Fixed-strike straddle. You pick a strike, say the 9:20 ATM, and follow that exact pair all day. This is the line for a trader who has sold or bought that straddle. As the index moves away from the strike, one leg gains intrinsic value and the combined premium climbs, even while time decay is working against it.
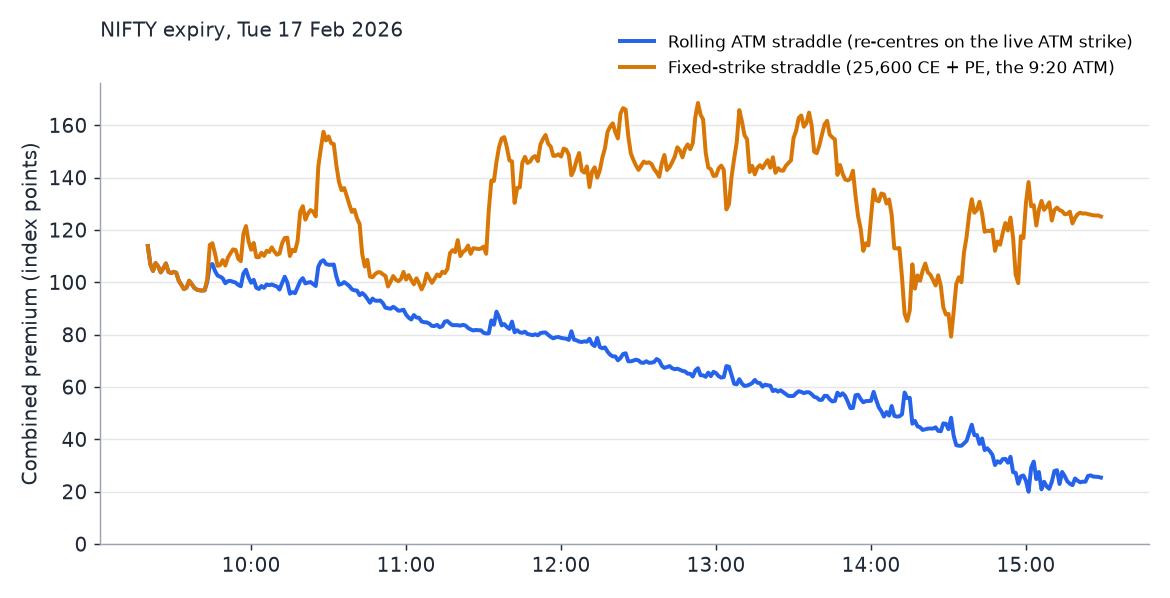
Here is the same NIFTY expiry on both lines. Tuesday 17 February 2026, index near 25,580 at 9:20, so the ATM strike was 25,600 and both lines start at the same value, 113.8 points.
| Time | Index | Rolling ATM straddle | Fixed 25,600 straddle |
|---|---|---|---|
| 9:20 | 25,580 | 113.8 | 113.8 |
| 10:00 | 25,660 | 99.8 | 112.4 |
| 12:00 | 25,730 | 78.8 | 148.0 |
| 2:00 PM | 25,705 | 54.8 | 125.0 |
| 3:29 PM | 25,716 | 25.4 | 125.2 |
The rolling line fell in a clean slope, because it kept re-centring and shedding time value. The fixed line did not. By noon the index sat 130 points above 25,600, so the put was nearly dead but the call carried real intrinsic value, and the pair was worth more than at the open. Someone looking only at the rolling chart that day would have said premium was melting. Someone short the 25,600 straddle would have seen something else entirely. Neither chart was wrong. They answer different questions, so know which one is on your screen.
This is also why an open position follows the fixed line, not the rolling one. The position itself is covered in our short straddle explainer.
What Moves the Line: Time, Volatility and Distance
Three forces, and you can usually tell them apart.
- Time (theta). Every option loses time value as expiry nears, and the loss speeds up near the money. This is the steady slope on a rolling chart. The mechanics are in our guide to what actually decays in an option.
- Implied volatility (vega). If traders pay more for protection or movement, both legs get dearer and the straddle rises with the index standing still. If they stop caring, both legs cheapen. Implied volatility explained covers where that number comes from.
- Distance from the strike (gamma). This only moves a fixed-strike line. The further the index travels from the strike, the more one leg is worth. Near expiry it happens fast, which is why the Greeks behave so differently on expiry day.
Events add a fourth habit worth knowing. Ahead of a known event such as a policy decision, a budget or results from index heavyweights, traders bid up options and the rolling straddle drifts up or fails to decay on schedule. When the news lands, implied volatility often falls hard even if the index moves, a drop usually called IV crush. A buyer can be right on direction and still lose to it. A seller is on the other side of that trade, and carries the tail if the move is bigger than priced. We do not have a clean enough event log to put a number on the crush, so we leave it as the pattern to watch for, not a statistic.
The Opening Value Is the Market's Price for the Day's Move
The straddle at 9:20 is the most useful single number on the chart, because it is the market's price for how far the index may travel by expiry.
For an at-the-money option, the straddle is about 0.8 times spot times implied volatility times the square root of the time left. Read that as: the straddle is roughly the average distance the index is expected to finish from where it is now. One standard deviation is about 1.25 times the straddle. Many traders use the shortcut of 0.85 times the straddle for the range the index stays inside on a typical day. That shortcut is really the median move, not a one-sigma move.
We checked it against our sessions. On NIFTY expiry days, the 9:20 straddle had a median of 115.6 points (middle half of days: 96.8 to 137.3), which is about 0.46% of the index. At lot size 65 that is roughly Rs 7,500 of premium on one lot. On SENSEX the median was 370 points, also about 0.46% of the index, or roughly Rs 7,400 on a lot of 20. The gap between the 9:20 and 3:29 index levels had a median of 0.82 times the opening straddle on NIFTY and 0.81 on SENSEX. So the shortcut held up as a median.
Two cautions. A median says nothing about the days that break it: the middle half of NIFTY sessions ran from 0.43 to 1.35 times the opening straddle, and a quarter of them went past 1.35. And this is a description of the market, not of any trading rule. It leaves out costs, stop-losses and slippage, and it is not a profit figure.
The Expiry-Day Clock: What the Rolling Line Normally Does
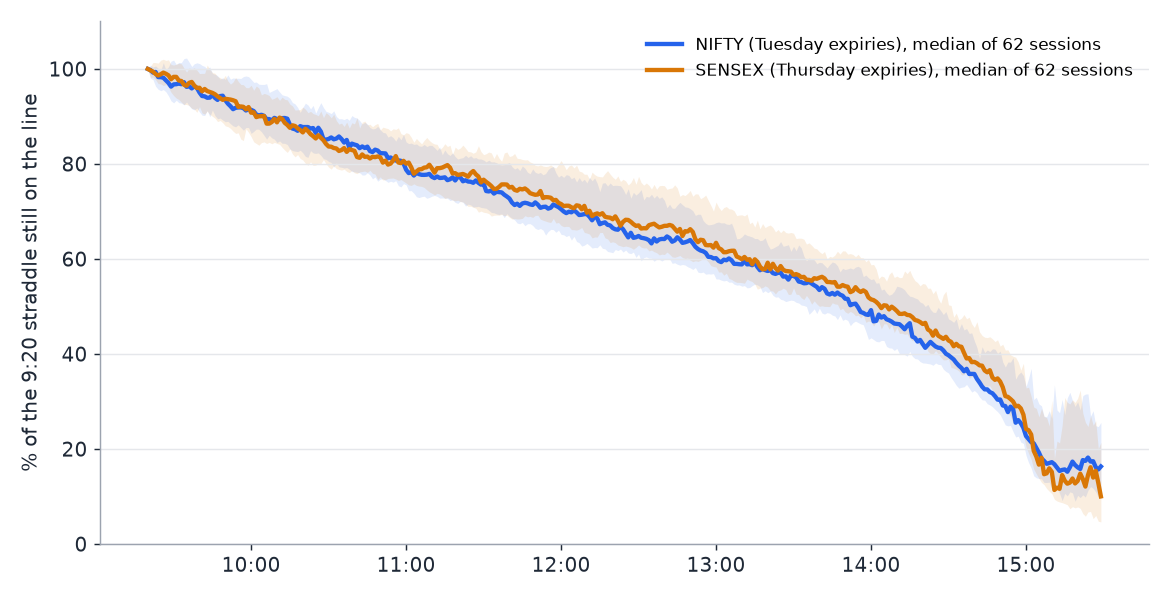
If you want one baseline to hold the line against, use this. For each session we divided every minute's rolling straddle by its 9:20 value and took the median across sessions.
| Time | NIFTY median | NIFTY middle half of sessions | SENSEX median |
|---|---|---|---|
| 9:30 | 97% | 93% to 102% | 98% |
| 10:00 | 91% | 86% to 98% | 91% |
| 11:00 | 79% | 76% to 85% | 80% |
| 12:00 | 71% | 65% to 78% | 72% |
| 1:00 PM | 60% | 56% to 68% | 63% |
| 2:00 PM | 49% | 43% to 56% | 52% |
| 3:00 PM | 23% | 19% to 33% | 24% |
| 3:29 PM | 16% | 10% to 26% | 10% |
What stands out, and where this corrects a common belief:
- The morning is slower than people say. By 10:00 the median NIFTY line had shed only about 9% of its opening value. The first 45 minutes are not where most of the decay happens.
- Half the premium is still there at 2:00 PM. The median line still held about 49%. About 33 percentage points of the opening value went between 2:00 and 3:29, so the back end carries a large share of the decay.
- The last 90 minutes are the steepest and the widest. The middle-half band is 43% to 56% at 2:00 and 19% to 33% at 3:00. The curve bends hardest exactly where sessions disagree most.
- The line is not flat at the close. At 3:29 PM the median NIFTY session still had 16% of its opening straddle on the line. We stop at 3:29 because that is the last cash index print, and the ATM anchor is shaky after it.
For the hour-by-hour behaviour of premium on the same days, see our piece on the NIFTY expiry-day premium clock.

Four Shapes Worth Naming
Against that median curve, the line does one of four things. We use these names when we review a session. We have not measured how often each shape shows up, and we will not quote a percentage we cannot back.
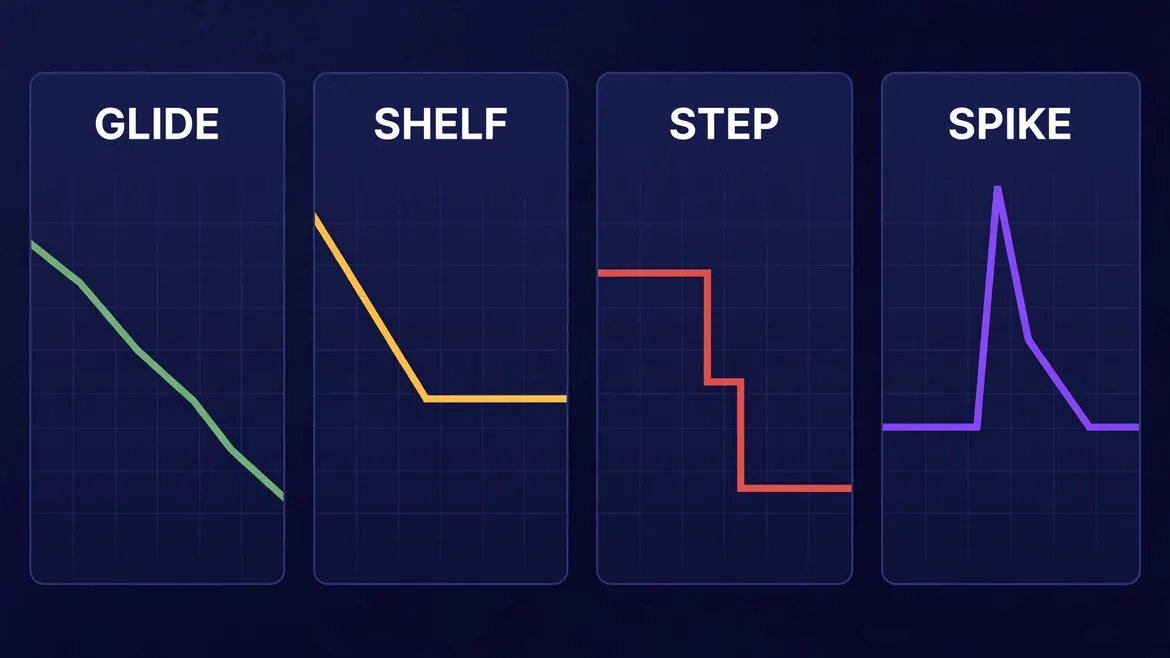
- Glide. A steady fall close to the median curve. Time is beating movement. This is the quiet day.
- Shelf. The line stops falling and sits level for a while. Falling time value is being offset by rising implied volatility, which usually means the market is waiting on something. Check the VIX line before reading anything into it.
- Step. One sharp drop. Most often it is IV crush after news, or a strike change on a thin strike. Look at whether the index moved at the same moment.
- Spike. The line rises well above where it was. If it comes with a sustained index move over several minutes, it is a genuine repricing.
How big can a spike get? We measured the largest rise from the session low after 1:00 PM, as a share of the opening straddle. The median NIFTY session had a rise of about 11%. One session in four had 16% or more, and the biggest was 41%.
Here is a real one. Tuesday 2 September 2025, the first Tuesday session in our sample. The rolling line was at 47.5 at 1:00 PM and bottomed near 45 before the 2:07 PM peak. Then the index fell about 105 points in 22 minutes, from 24,650 at 1:45 to 24,544 at 2:07 PM. The line went from 51.6 to 71.8, a rise of about 27 points from the low, a third of the 84.0 it had opened at. It did not stay: by 3:00 PM it was 26.8, and by 3:29 PM 20.4. The spike was real, it came with a sustained move, and it faded.
| Time | Index | Rolling ATM straddle |
|---|---|---|
| 9:20 | 24,654 | 84.0 |
| 1:00 PM | 24,740 | 47.5 |
| 1:45 PM | 24,650 | 51.6 |
| 2:07 PM | 24,544 | 71.8 |
| 3:00 PM | 24,573 | 26.8 |
| 3:29 PM | 24,575 | 20.4 |
Strike Changes: The Jump That Is Not News
A rolling chart re-centres on the strike nearest the index. When the index crosses the midpoint between two strikes, the chart switches strikes. In a clean market the two straddles are nearly equal at the midpoint, so the line should barely notice. In practice it often steps, because the new strike trades less often and its last print can be stale, and because puts and calls do not price symmetrically.
We counted it. A strike-change minute moved the NIFTY line by a median of 3.5% of its opening value, against 0.9% for an ordinary minute, so a change moves the line three to four times as much. We counted strike changes two ways. Counting every minute in which the nearest strike differed from the minute before, including flips back and forth while the index sits near a midpoint, the median was 38.5 per session on NIFTY and 72 on SENSEX. Counting only changes that held for at least five minutes, the median was 10 per session on NIFTY (middle half 7 to 13) and 15 on SENSEX (13 to 17). The second count is the better picture of how often the line really re-centres. SENSEX changes strike more often because its 100-point grid is finer against the index level than NIFTY's 50-point grid. That is the honest answer to "why is my SENSEX line twitchier".
The test before you react: did the index cross a strike midpoint at that minute, and is the move one tick or a run of minutes? One tick that coincides with a crossing is probably mechanical.
Where the Chart Misleads
- The first minutes. Spreads on the strikes are wide just after 9:15 and the first prints are poor. We read the opening value at 9:20, not at 9:15.
- Stale prints. A strike that has not traded in a few minutes shows its last price. We carried the last traded price forward in our data. That is fine at the money and unreliable away from it.
- Comparing across a strike change. The 10:00 and 2:00 values may belong to different strikes. Percent-of-open handles that for the rolling line. It does not for the fixed line.
- Reading days against each other. A 100-point straddle with six hours left and one with six days left are different things. Compare like with like: same time, same days to expiry.
- The closing minutes. The index tape stops at 3:29 PM while option bars run on. The ATM anchor in the last ten minutes rests on one index print.
Reading It Next to the Synthetic Future and VIX
A synthetic future (long call, short put at the same strike) moves almost one-for-one with the index and tells you about direction. The straddle tells you about pricing. Put them on the same screen and the two stories separate: a falling straddle with a rising synthetic means the index is trending while volatility is being sold. Zerodha Varsity's straddle chapter is the standard reference for why a short straddle is a bet that movement stays inside the premium collected.
India VIX is a month-ahead measure. It will not match an expiry-day straddle point for point. Use it as a cross-check on a shelf or a spike: a shelf with VIX rising looks like a market pricing something. A shelf with VIX flat is more likely a quiet drift. How VIX relates to the premium a seller can expect is in our India VIX and premium budget note.
A word on tools. Groww's straddle chart, Sensibull's multi-straddle view, AlgoTest's charts and Dhan's straddle chart all draw a good live line. We do not rank them here. The skill is in the reading, and the reading is the same on any of them. For the payoff-chart builders, which are a different tool from a live straddle chart, see Opstra vs Sensibull payoff charts.
A Short Pre-Session Checklist
- Know which line is on screen: rolling ATM or fixed strike.
- Note the 9:20 value and divide by the index level. Around 0.4% to 0.6% has been normal on our sessions. Well above that, ask why.
- Compare the line with the median curve above at 10:00, noon and 2:00 PM. Far above it means movement is being paid for. Far below means decay is ahead of schedule.
- Before reacting to a jump, check if the index crossed a strike midpoint.
- Keep the VIX line next to any shelf.
- Treat 2:00 PM to the close as the window where the line is steepest and the sessions differ most.
Paper trade every framework in this article first. This is analytical research from our own data, not advice and not a signal. The curves describe the market; they are not the result of a strategy and say nothing about costs or stops. If you want to turn a read like this into a rule you can test, start with how to backtest an option-selling strategy, and see why a simulator is not a backtest.
How We Built This Data Set
For each NIFTY and SENSEX expiry session from September 2025 to early November 2026 (62 each), we took one-minute option bars from our historical store. Each minute we found the strike nearest the index close (50-point grid for NIFTY, 100 for SENSEX), added that strike's call and put closes, and carried the last traded price forward when a strike had no trade. We measured from 9:20 to 3:29 PM. A handful of sessions fall on a Monday or Wednesday because of exchange holidays. The fixed-strike line uses the 9:20 ATM strike.
What this does not do: it does not simulate a trade, include costs or stops, or say any rule makes money. It also covers a short window, and a calm or stormy stretch would shift the medians. Treat the medians as a baseline for what a line normally does, not a forecast.
Further Reading on This Site
- Short straddle explained, and how it compares with a strangle in short straddle vs short strangle on NIFTY.
- Long straddle vs long strangle, the buyer's side of the same chart.
- NIFTY short straddle concentration risk.
- SENSEX weekly expiry option selling.
- How option premium is priced strike by strike and ITM, OTM and ATM.
Frequently Asked Questions
What is a straddle chart?
A straddle chart plots the combined premium of one call and one put at the same strike and expiry, minute by minute. Most tools use the at-the-money (ATM) strike and re-centre it as the index moves, which is why it is also called a rolling ATM straddle. A fixed-strike straddle chart tracks one pair of options all day instead.
What does it mean when the NIFTY ATM straddle is going down?
It means the combined price of the ATM call and put is falling. Three things can cause that: time passing (theta), implied volatility dropping, or, on a fixed-strike chart only, the index drifting back toward the strike. On a rolling ATM chart the first two are what you are seeing. On expiry day a steady fall is normal. On our data the median NIFTY expiry session had about 49% of its 9:20 straddle left at 2:00 PM and about 16% left by 3:29 PM.
What is the difference between a rolling ATM straddle and a fixed-strike straddle?
The rolling line always shows the pair that is at the money right now, so it behaves like a volatility-and-time gauge and mostly slopes down on expiry day. The fixed-strike line shows the pair you would have sold at a given moment. It gets pushed up whenever the index moves away from that strike, so it can rise all afternoon while the rolling line falls. A seller needs both: the rolling line to judge the market, the fixed line to see what the open position is worth.
How do you read a straddle chart on expiry day?
Read the shape against the typical decay curve, not the level. In our sample the median NIFTY line kept 91% of its 9:20 value at 10:00, 71% at noon, 49% at 2:00 PM and 23% at 3:00 PM. A line well above that curve means the market is paying for movement. A line well below it means decay is running ahead of schedule. A sharp rise in the afternoon that comes with a sustained index move is a real repricing, not noise.
How big a move does the ATM straddle price in?
Roughly the average absolute move to expiry. For an at-the-money option the straddle is about 0.8 times spot times implied volatility times the square root of time, so one standard deviation is about 1.25 times the straddle. The popular shortcut of multiplying the straddle by 0.85 gives the median move, the distance the index stays inside on about half of all days. In our 62 NIFTY sessions the median gap between the 9:20 and 3:29 index levels was 0.82 times the 9:20 straddle, which sits right on that shortcut.
Why does the straddle line jump suddenly?
Two common reasons. The first is a strike change: the ATM strike moves to the next strike as the index crosses the midpoint, and the line can step because the new strike trades less often and its last print is stale. In our data a strike-change minute moved the line about 3.5% of the opening value, against 0.9% for an ordinary minute. The second is a real repricing, which comes with a sustained move in the index over several minutes, not a single tick.
What is the difference between a straddle chart and a synthetic future chart?
A synthetic future (long call, short put, same strike) moves almost one-for-one with the index and says little about volatility. A straddle chart is close to direction-neutral near the money and shows how much the market is charging for movement and time. Use the synthetic or the index chart for direction, the straddle chart for pricing.
Can the straddle chart predict market direction?
No. It prices how far the index may move, not which way. Some traders compare it with the index for clues, but that is a judgement call, not a signal, and nothing here tests it as one.
Which days are NIFTY and SENSEX expiry days, and what are the lot sizes?
As of November 2026, NIFTY 50 weekly options expire on Tuesday and SENSEX weekly options on Thursday, moved to the previous trading day when the exchange is closed. The NIFTY lot is 65 and the SENSEX lot is 20, so one straddle point is worth Rs 65 on a NIFTY lot and Rs 20 on a SENSEX lot. Check the exchange circulars before you size anything, because lot sizes get revised.
Should I trade live based on straddle chart patterns?
Paper trade any framework from this article first. EliteAlgo publishes analytical software and research, not investment advice. The decay curves here describe the market, not the result of any trading rule, and they carry no costs, stop-losses or slippage. Test your own rules before real capital goes anywhere near them.