If you have spent even a week around Indian options traders, you have heard it: "sellers make money, buyers lose money." It is half true, and the half that is missing is what hurts people. A Nifty option selling strategy for beginners rests on one structural fact. Time decay works for you instead of against you. That is why so many traders move from buying options to selling them. It is also why so many of them hand the money back in one bad session.

Selling options is not "safer" by default. You swap one risk (losing the whole premium you paid) for another (losing several times the premium you collected). The sellers who last are not the ones with a secret setup. They know the mechanics well enough to size small, cap the bad day and repeat the same boring process for hundreds of trades.
This guide covers what Nifty option selling is, the numbers you need on day one (lot size, margin, costs, tax), four building-block strategies, a fully worked iron condor in rupees, how to size a position, and how a beginner should spend the first three months. It is written from the desk's side: we run rule-based Nifty and Sensex expiry-day selling, so we have made most of these mistakes in some form.
The Short Version
- One Nifty lot is 65 units. Every point of Nifty is worth Rs 65 to you per lot.
- Weekly Nifty options expire on Tuesday (the previous trading day if Tuesday is a holiday).
- A naked short lot blocks roughly Rs 70,000 to over Rs 1.1 lakh of margin on our desk. A hedged spread blocks far less.
- Start with a defined-risk spread, one lot, after at least a month of paper trading first.
- Size from your maximum loss, not from the margin your broker asks for.
- STT on the option sell leg is 0.15 percent of premium from 1 April 2026. Profits are business income, not capital gains.
Disclaimer: This article is for education only. EliteAlgo provides analytical and execution software. It does not provide investment advice, and nothing here is a recommendation to buy or sell any security. Options trading carries a substantial risk of loss and is not suitable for everyone. All rupee examples are hypothetical illustrations, not live quotes or results. Read SEBI's risk disclosures for derivatives before you trade.
What Is Option Selling in the Nifty Index?
When you buy a Nifty call or put, you pay a premium for the right (not the obligation) to buy or sell the index at a fixed strike before expiry. When you sell (also called "write") the same option, you are on the other side. You collect the premium now, and you take on the obligation to pay out if the option finishes in the money. Nifty options are cash-settled, so nobody delivers any shares. You simply pay or receive the difference in rupees. For the legal side of that obligation, see being the option writer.
Options are a decaying asset. Every day that passes, if the index does not move much, an option loses some of its value. That loss is called theta or time decay. As a seller you are paid for it. As a buyer you fight it. The decay is not even. It is slow with weeks to go and fastest in the last few sessions for options near the money, which is why a large share of selling is done in the final days before expiry. Our expiry-day premium clock measures how that decay actually behaves hour by hour on Nifty expiry day.
Nifty weeklies are among the most heavily traded index options in the world, so spreads are tight and your orders fill close to where you expect. That matters more for sellers than buyers, because the exit has to work on the one day you need it.
Why Beginners Are Drawn to Option Selling
- You can be right in more ways. A seller of out-of-the-money options wins if the market goes sideways, drifts a little either way, or even moves a bit against them. A buyer needs a big move in the right direction.
- It looks like rent. You collect a premium for providing insurance, and most weeks the insurance is not needed.
- Frequent cycles. A weekly expiry gives you a fresh decay cycle every week instead of every month.
But a high chance of profit is not the same as a good bet. A trade that wins 80 percent of the time and loses five times its average win on the other 20 percent has an average result of zero before costs, and a negative result after them. Judge a strategy by what the average win and average loss are, not by how often you are right. This is the single most important idea in this article, and we will put numbers on it below.
The Numbers You Need Before Your First Trade
Most beginner guides talk about strategy and skip the arithmetic that decides whether you survive. Here is the short list for Nifty as of November 2026. Rules change, so confirm anything that affects real money on NSE, SEBI or your broker's site.
| Item | Where it stands | Why a beginner cares |
|---|---|---|
| Nifty lot size | 65 units. NSE cut it from 75 in its December 2025 revision. | Rupees per point = 65. A 100-point move is Rs 6,500 per lot. Older articles quoting 75, 50 or 25 are out of date. See NIFTY lot size and position sizing. |
| Weekly expiry | Tuesday for Nifty. If Tuesday is a holiday, the previous trading day. | Old guides say Thursday. Plan your week around Tuesday. |
| One weekly expiry per exchange | SEBI limited each exchange to one weekly benchmark index from late 2024. | That is why Nifty has weeklies on NSE and Bank Nifty weeklies are gone. See why Bank Nifty weeklies ended. |
| Margin for a naked short lot | SPAN plus exposure. On our desk a strangle lot has blocked roughly Rs 70,000 to over Rs 1.1 lakh, depending on strikes and volatility. | It changes through the day. Margin is not your maximum loss. See SPAN and exposure margin on a Nifty strangle and NSE calculator vs broker margin. |
| Expiry-day rules | No calendar-spread margin benefit on expiry day. Positions are checked against limits during the day, not just at close. | A hedge that lowered your margin on Monday may not lower it on Tuesday. Keep a cash buffer. |
| STT on options | 0.15 percent of premium on the sell leg from 1 April 2026 (earlier 0.10 percent). An exercised option attracts a separate 0.15 percent charge on intrinsic value, paid by the purchaser, not the seller. | Square off an in-the-money short before expiry for settlement-price and gamma risk, not to save STT. See the STT rule sellers get wrong. |
| Tax | F&O profit and loss is business income, taxed at your slab, not capital gains. | Keep records from day one. See how options trading is taxed in India. |
Take the STT line seriously. At 0.15 percent on the premium of the sold legs, a small trade costs only a few rupees, but a seller who trades several lots every day pays it again and again. Add brokerage, exchange charges and GST, and costs become a real input to your strategy, not a rounding error. Any backtest that ignores them is flattering you. We cover that in how to backtest an option selling strategy.
The Core Building Blocks: Strategies Beginners Should Understand First
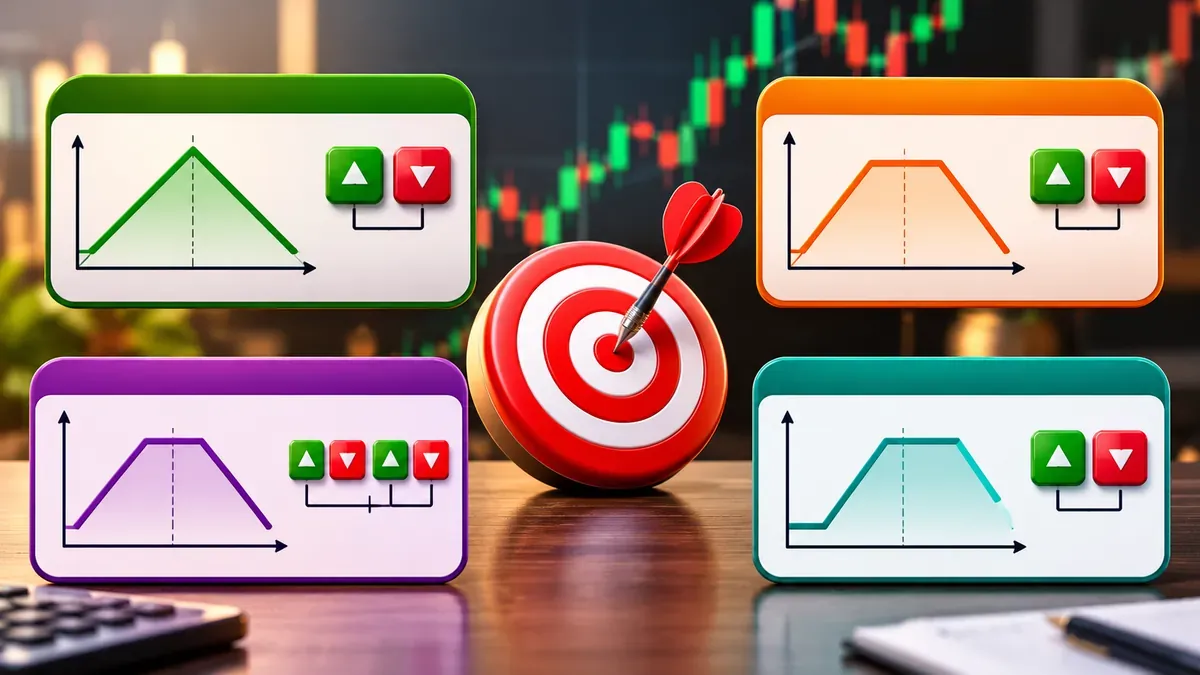
You do not need to memorise twenty strategy names. Nearly every serious Nifty selling approach is built from four structures.
1. Short Straddle
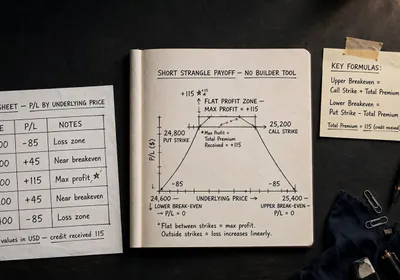
Sell an at-the-money (ATM) call and an ATM put at the same strike and expiry. You collect the most premium of any structure because ATM options carry the most time value. You profit if the index finishes close to that strike. The loss is open-ended on both sides if the market moves hard. Full mechanics in short straddle explained.
2. Short Strangle
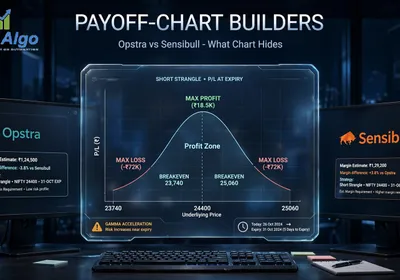
Sell an out-of-the-money (OTM) call and an OTM put at different strikes. You collect less than a straddle but the index has more room before either leg is in the money. The risk is still open-ended. See short strangle explained, and straddle vs strangle on Nifty for how the two compare on real expiries.
3. Iron Condor
A short strangle plus two bought options further out, one on each side. Those bought wings cap the maximum loss. You pay for the cap with a smaller credit. For a beginner this trade is often worth it, because it removes the tail risk that ends accounts. We explain why our own desk prefers it in iron condor vs naked strangle. If you want a version that is even more tightly capped, read about the iron butterfly.
4. Credit Spreads (Bull Put and Bear Call)
Sell one option and buy a further OTM option of the same type. A bull put spread wants Nifty flat or higher. A bear call spread wants it flat or lower. They have a smaller credit and a capped loss, and they are usually the first real strategy a beginner should trade live. More in vertical spreads: when we cap risk and credit spreads and the defined-risk strangle.
| Structure | Max profit | Max loss | Margin | Fit for a first live trade? |
|---|---|---|---|---|
| Short straddle | Full premium (highest) | Open-ended both sides | High | No |
| Short strangle | Full premium | Open-ended both sides | High | No |
| Iron condor | Net credit | Wing width minus credit | Much lower | Yes, after paper trading |
| Bull put or bear call spread | Net credit | Strike gap minus credit | Low | Yes, usually the easiest start |
| Covered call or cash-secured put | Premium | Large (you own the stock or hold the cash) | Own shares or cash | Works on stocks. See covered calls and cash-secured puts |
Direct answer for readers who want a quick take: if you are a true beginner, start with a credit spread or an iron condor, not a naked short straddle or strangle. The premium is smaller, but so is the chance that one trade erases weeks of gains. Move to open-ended strategies only after you have a risk framework you have tested on paper and a position size you can survive being wrong at. Be wary of anything sold as "zero risk" or "guaranteed", and read the zero-risk option strategy myth before paying anyone for one.
A Worked Example: One Iron Condor Lot, in Rupees
Numbers make the risk real. This is a hypothetical example to show the arithmetic, not a live quote or a recommendation. Assume Nifty is at 24,500 a few days before Tuesday expiry and the premiums below are what the market is offering.
| Leg | Action | Premium (points) |
|---|---|---|
| 24,800 call | Sell | 40 |
| 25,000 call | Buy (wing) | 15 |
| 24,200 put | Sell | 42 |
| 24,000 put | Buy (wing) | 16 |
| Net credit | 51 points |
- Credit collected: 51 points times 65 = Rs 3,315 per lot, before costs.
- Maximum loss: the wings are 200 points wide, so (200 minus 51) times 65 = Rs 9,685 per lot. This is the worst case on either side, and you know it before you enter.
- Break-evens: 24,200 minus 51 = 24,149 on the downside, and 24,800 plus 51 = 24,851 on the upside.
- The win rate you need: you risk Rs 9,685 to make Rs 3,315. To break even you must win about 75 times out of 100 (9,685 divided by the sum of 9,685 and 3,315). That is before brokerage, STT and GST, so you need more than 75.
- STT on the sold legs: premium sold is (40 plus 42) times 65 = Rs 5,330, and 0.15 percent of that is about Rs 8. Small on one lot, but add brokerage, exchange charges and GST on every order, then multiply by every week of the year.
Now compare this to selling only the two short legs (a plain strangle). You would collect 82 points, or Rs 5,330, and block over a lakh of margin, but your loss would have no cap. The condor gives up Rs 2,015 of credit to buy a known worst case. On a quiet week that looks expensive. On a gap day, it is the cheapest thing you ever bought.
One more point from this example. The maximum loss of Rs 9,685 on one lot is a lot for a small account. If you follow the 1 to 2 percent rule below, one lot of this condor needs roughly Rs 5 to 10 lakh of capital behind it. If your account is smaller, use narrower wings (100 points wide caps the loss lower, at the cost of a smaller credit), or stay on paper longer.
Step-by-Step: How a Beginner Should Approach the First Nifty Option Selling Trade
Step 1: Understand the Expiry Calendar
Nifty weeklies expire on Tuesday, and the expiry moves to the previous trading day on a holiday. Decay is not linear. It is slowest with many days to go and steepest in the last one or two sessions for options near the money. That acceleration is exactly why sellers target it, and also why a small move late in the day can swing premium sharply. If you plan to sell on expiry day itself, read option greeks on expiry day first. Gamma, not theta, is what bites you on that day.
Step 2: Choose Strike Distance from Volatility, Not Habit
A common beginner mistake is "always sell 200 points out." The distance that gives you the same chance of finishing safe changes with implied volatility (IV) and India VIX. When VIX is high, premiums are richer but the expected range is also wider, so the same 200 points is much closer to trouble. A fixed distance in a high-VIX week is how many beginners get hurt on a single volatile session. Use a rule such as a delta level or a multiple of the expected move, and write it down. Our India VIX premium budget shows one way to tie strike distance to VIX. Also make sure the strikes you pick have real volume and open interest. Thin strikes give wide spreads and poor exits (see liquidity before IV). For the terms, implied volatility explained and ITM, OTM and ATM cover the basics.
Step 3: Size the Position Before You Enter, Not After
Work out your size from the maximum loss you are willing to take, never from the premium you would like to collect. A workable starting discipline is to risk no more than 1 to 2 percent of trading capital on any one expiry cycle. Take the condor above: the worst case is Rs 9,685 per lot. At 2 percent risk, you need about Rs 4.85 lakh. At 1 percent, about Rs 9.7 lakh. If that is more than you have, the answer is a narrower spread or fewer rupees at risk, not a bigger lot count. Keep extra cash beyond the margin shown, because margin can rise during the day. More on this in position sizing vs technique.
Step 4: Define Your Exit Rules in Advance
Every selling strategy needs three exits written down before entry:
- Profit target: many sellers close at 50 to 70 percent of the maximum credit instead of waiting for the last few rupees. The last 20 to 30 percent rarely pays for the tail risk of holding on.
- Stop loss: a hard rule, often a multiple of the premium collected (for example 2x), or a spot level. For a naked short, a stop can slip badly in a fast market. A spread's wings are your final stop. See trailing stop loss for short options.
- Time or event exit: some sellers close before RBI policy, Union Budget day or major global events regardless of where the trade stands, because gap risk breaks normal models.
Also decide what you do with an in-the-money short on expiry afternoon. The clean answer is to square it off yourself before the close. That is about settlement-price and gamma risk, not tax, because a short leg pays no extra STT at settlement. Our note on square-off for the option seller explains why. For how expiry settlement works at the close, see the SEBI closing auction session and expiry settlement page.
Step 5: Track Results Like a Business, Not a Bet
Log every trade: strikes, IV or VIX at entry, credit, exit reason, costs, and net P&L. After 20 to 30 trades the patterns show up: which distances, which weekdays and which volatility levels work for you. A simple table is enough. The log also does your tax work for you, since F&O profit is business income and you will need turnover and expense detail at filing time.
Risk Management: The Part Most Beginners Skip (and Regret)
This page is scoped to a beginner's first Nifty trade. For the full catalogue of selling structures (naked, defined-risk and asset-backed, index and stock), see option selling strategies explained. This section matters more than strategy choice. It is usually the difference between traders who last five years and those who last five months.
Naked Selling Has Open-Ended Risk
A short call without a hedge has unlimited loss potential. A short put has very large loss potential, bounded only by the index going to zero. Gaps are the problem. On 4 June 2024, the day of the general election result, Nifty closed down 5.93 percent, a fall of about 1,380 points. At today's lot size of 65, a move that size is around Rs 90,000 against one short put lot, in one session, with no chance to exit at your stop. Whatever your stop-loss says, your real exit is wherever the market lets you out.
Defined-Risk Structures Exist for a Reason
That is why iron condors and credit spreads exist. They cap the loss at a known number the moment you enter. For a beginner, knowing the worst case in rupees before clicking sell is not a nice extra. It is the whole point of using a spread instead of a naked position. For how a desk hedges when it does sell naked, see hedging an option selling position and when and how we actually hedge a naked strangle.
Margin and Leverage Discipline
Exchanges require margin for short options, and it can jump when volatility rises (budget day, election results, global sell-offs). Because positions are now checked against limits during the day, a sudden rise can leave you short of margin even if your trade has lost nothing yet. A forced square-off tends to happen at the worst price. Hold extra cash above the margin shown, and never run your account at full utilisation.
The Emotional Trap: Averaging Down on a Losing Short
The most common way a beginner turns a manageable loss into an account-threatening one is by selling more options against a losing position to "improve the average." That adds size exactly when the trade has shown the idea is wrong. A stop-loss followed mechanically exists to stop this behaviour.
What Option Selling Does Not Fix
Option selling will not turn a small account into a salary. A strategy that earns, say, a few thousand rupees a lot in good weeks also loses a few multiples of that in bad ones. Expect long flat stretches and the occasional sharp loss. If you need the money you are trading with, you are not ready to sell options.
Why Algorithmic Execution Changes the Equation for Beginners
Strike selection tied to VIX, stop-loss and profit rules, position size set before entry, a trade log. All of this is a set of rules. Rules are easy to write and very hard to follow when real money is moving against you on a live screen.
That is the problem algorithmic execution solves for sellers. A system does not feel fear when a position is red. It does not get greedy and hold past a target "just in case." It runs the rule exactly as written, every cycle. That is the discipline beginners struggle with most when trading by hand. It does not make a bad rule good, though, so the rule has to be tested first (see what a backtest can and cannot prove), and run in paper mode before real money.
At EliteAlgo this is how our systems are built for Nifty and Sensex expiry-day and weekly selling: entry logic tied to volatility conditions, fixed stop-loss and profit rules, and set position sizing, run the same way whatever the trade feels like at that moment. If you want to see the idea applied to a real broker API, read automating an option selling strategy on Zerodha Kite. And if you are comparing tools, best options backtesting software in India lists the main ones.

Your First Three Months: A Plan That Does Not Blow Up
- Weeks 1 to 2: learn the vocabulary. Strike, premium, moneyness, expiry, delta, theta, vega. Option greeks explained and what is an option chain are enough to start. Read option buying vs option selling to see which side suits your temperament.
- Weeks 3 to 6: paper trade first. Run the same iron condor or credit spread every week on paper, with your real exit rules and a written log. Count what you would have paid in costs. The goal is not profit. The goal is to see if you can follow your own rules.
- Weeks 7 to 10: one lot, defined risk, live. Use the smallest size that fits your 1 to 2 percent rule. Keep logging. Do not add lots after a win.
- Weeks 11 to 12: review. Look at average win against average loss, worst day, and how often you broke your own rule. If you broke it often, fix that before you add risk. Only then think about wider strategies or automation.
Treat any week where you break a rule as a loss, even if the trade made money. That habit alone separates traders who improve from traders who repeat.
Common Mistakes Beginners Make in Nifty Option Selling
- Using old numbers such as lot size 75 or Thursday expiry from an out-of-date guide.
- Ignoring VIX regime shifts and using the same strike distance in calm and volatile weeks.
- No predefined stop-loss, treating each trade as "it will come back."
- Sizing from premium instead of from maximum loss.
- Holding through major events: RBI policy, Union Budget, US Fed decisions, election results.
- Naked selling without understanding margin expansion, then being force-squared off at the worst price.
- Forgetting costs, including STT on every sell order, so the contract note is a surprise.
- No trade journal, so the same mistakes repeat.
- Treating a high win rate as proof without checking the size of the occasional big loss.
- Buying a "guaranteed" course or signal service before testing the idea yourself. Our view is in option trading course: worth it or backtest?
Frequently Asked Questions
Is option selling profitable for beginners in Nifty?
What is the safest option selling strategy for a beginner in Nifty?
How much money do I need to sell one lot of Nifty options?
What is the Nifty lot size and expiry day now?
Can I start option selling with Rs 1,000 or Rs 10,000?
Is there a strategy with a 90 percent win rate?
Can algo trading help beginners with option selling?
Is option selling riskier than option buying?
Does SEBI regulate algo trading and option selling for retail traders?
Where to Go Next
Understanding the mechanics is step one. A consistent, rule-based process that you actually follow over dozens of cycles is what decides results. Good next reads:
- How to sell options, step by step for the mechanics of one short position.
- Option selling strategy for monthly income on Nifty if you prefer a slower cycle than weeklies.
- Getting started with algo trading in India for how algorithmic execution works for Indian index derivatives.
- Nifty & Sensex algo trading strategies for how EliteAlgo structures systematic strategies on these two indices.
- SEBI algo trading regulations explained for the framework every systematic trader should know.
- EliteAlgo trading strategies overview for the range of systematic approaches.
- Frequently asked questions for platform and onboarding questions.
For official information, go to NSE for contract specifications, lot sizes and expiry days, and to SEBI's investor resources for derivatives rules and risk disclosures. For a deeper grounding in option pricing and theta, the Cboe Options Institute and the Options Industry Council both publish free educational material.
This article reflects EliteAlgo's research desk analysis of publicly available options trading mechanics and is for education only. EliteAlgo builds analytical and execution software for systematic Nifty and Sensex option strategies. It does not provide personalised investment advice. Figures marked as examples are hypothetical. Trading in derivatives involves substantial risk of loss and may not suit every investor. Assess your own risk tolerance, and consider speaking to a qualified financial adviser if needed.